Building a crowdfunding platform means engineering a financial product — not a content site. Under the surface of every successful platform like Kickstarter, Indiegogo or Fundrise sit interconnected systems: escrow logic, investor verification, payment distribution, compliance controls, and a secondary market for traded assets. This guide walks through every architectural and crowdfunding business decision you need to make before writing a line of code, based on how we actually build these platforms — from MVP scope to production-grade systems serving regulated investors.
A crowdfunding platform monetizes at scale: Kickstarter keeps 5% of every successfully funded campaign. Indiegogo takes 5% from successful campaigns and 9% from partial ones. The business is viable — but only if your platform's architecture can handle the financial flows, compliance requirements, and user trust that make investors commit real money.
 Yuri MusienkoBusiness developer, Merehead
Step 1: Niche and Target Audience
The niche decision is the highest-leverage choice in the entire project. It determines your compliance requirements, your payment architecture, your KYC depth, and your smart contract needs — before you write a single functional spec.
Compare three different positioning choices and what they technically imply:
| Niche | Model | Compliance requirement | Critical technical module |
|---|---|---|---|
| Creative projects (film, music, games) | Reward-based | Low — no SEC registration | Campaign builder, escrow, reward management |
| Real estate investment | Equity / tokenized | High — SEC Reg CF or Reg A+, KYC/AML mandatory | KYC whitelist, token issuance, dividend distribution, secondary market |
| Charitable causes | Donation | Low to medium — depends on nonprofit status | Payment gateway, donor dashboard, campaign analytics |
| Business / startup equity | Equity / P2P lending | High — SEC, FINRA, accredited investor rules | Investor accreditation, legal document signing (DocuSign), escrow |
| Blockchain / crypto startups | Token / ICO | Variable — depends on token classification | Smart contract, wallet integration, token vesting, AML |
Popular niche platforms worth studying before you spec your own: Fundrise (real estate equity), Republic (startup equity), Patreon (creator subscriptions), Crowdcube (UK equity crowdfunding), SeedInvest (accredited investor equity).

Step 2: Crowdfunding Business Models

Five distinct models exist, each with different payout logic, legal exposure, and technical complexity:
- Donation-based. Backers contribute without expecting financial return. Simplest compliance profile. Suitable for charity, community projects, and small creative initiatives. Examples: Crowdrise, MightyCause. No escrow complexity — funds transfer directly or on campaign close.
- Reward-based. Backers receive a pre-defined reward — physical product, early access, exclusive experience — in exchange for their contribution. Kickstarter and Fundable run this model. Requires reward tier management, fulfillment tracking, and all-or-nothing escrow logic (funds held until goal reached, refunded if it isn't).
- Equity-based. Investors receive shares, profit participation rights, or a stake in the project. This is where SEC regulation enters: in the US, equity crowdfunding falls under Regulation Crowdfunding (Reg CF, capped at $5M/year per issuer) or Regulation A+ (up to $75M/year). Platform operators must register as a funding portal with FINRA. Investor accreditation verification is required above certain thresholds.
- P2P lending. Private investors fund loans and receive principal plus interest. Common alternative to bank loans for small businesses. Platform holds funds in escrow, distributes repayments on schedule. LendingClub, Prosper, and Funding Circle operate this model. Requires loan origination logic, amortization schedules, and default handling.
- Token / asset tokenization. Investors receive blockchain tokens representing ownership, platform access, or a share of revenue. Used for blockchain startups, tokenized real estate, and DeFi projects. Requires smart contract development, wallet integration, KYC/AML at the blockchain level (KYT — Know Your Transaction), and legal structure mapping (e.g., each token series backed by a separate legal entity).
After choosing a model, define your funding mechanics. Kickstarter uses strict all-or-nothing: if the goal isn't reached, no funds transfer and all escrowed amounts are released. IndieGoGo offers both all-or-nothing and flexible funding (keep whatever was raised). Equity platforms typically have a minimum raise threshold below which the offering is void. These rules are encoded into your escrow and campaign state machine — decide them before development starts.
Step 3: Monetization
Success fee (percentage of funds raised). The default model for most platforms. Kickstarter and IndieGoGo charge 5% of successfully funded campaigns. IndieGoGo charges 9% for campaigns that proceed under flexible funding without hitting the goal. Easy to understand for campaign creators, and aligns platform incentives with campaign success.
Listing fee. A one-time fee to list a project, common on equity crowdfunding platforms where SEC regulations prohibit charging a percentage of investment amounts. Fees vary by platform and deal size.
Service / loan origination fee. Used by P2P lending platforms. LendingClub charges 1% of each borrower payment. Landpay charges 2–2.5% for loan issuance and 0.5–1% annual margin fee on lenders. The fee structure is embedded in the amortization and distribution logic.
Subscription. Flat monthly fee for access to the platform's campaign tools. Fundable charges $179/month for unlimited projects. Works well for serial entrepreneurs and content creators who run multiple short campaigns.
Promoted listings and advertising. Paid placement on the homepage, top-of-listing positioning, or targeted recommendations to repeat investors. This is additive — almost always used alongside one of the above models, not as a standalone.
Step 4: Compliance and Investor Verification
This is the section most development guides skip or summarize in a bullet point. For any platform handling real money — especially equity, lending, or tokenized assets — compliance architecture is not a feature you add later. It's the foundation everything else is built on.
US Regulatory Framework
| Regulation | Model | Raise limit | Investor restriction | Platform requirement |
|---|---|---|---|---|
| Reg CF (JOBS Act Title III) | Equity / debt | $5M / 12 months | Non-accredited investors allowed with investment caps based on income/net worth | Must register as FINRA Funding Portal or broker-dealer |
| Reg A+ (Tier 2) | Equity | $75M / 12 months | Non-accredited investors allowed; no per-investor cap for accredited | SEC qualification required; ongoing reporting |
| Reg D (506b/506c) | Equity (private placement) | No limit | Accredited investors only (506c: verification required) | No SEC registration, but Form D filing required |
For non-US platforms: UK operates under FCA, Germany under BaFin, EU equity crowdfunding falls under ECSP regulation (harmonized since 2021, €5M limit). Always engage legal counsel before launch — the platform operator is liable for compliance failures, not just the campaign creators.
KYC/AML Architecture in Practice
In real-estate and equity crowdfunding projects, KYC is not a simple checkbox — it's an architectural decision that affects the entire investment flow. In one of our crowdfunding platform builds, we implemented a two-layer verification system: standard document-based KYC via an external provider, plus a manual whitelist approval step controlled by the admin. Only whitelisted users could access the "Invest Now" flow — users who registered but hadn't completed KYC were redirected to the verification step instead of the investment page.
This approach is required whenever the platform operates under SEC regulations or equivalent: you need a documented, auditable trail that each investor was verified before committing funds. Skipping this and adding it later means restructuring your entire authentication and routing logic — not just plugging in a KYC widget.
The practical consequence: plan your user state machine from day one with at least four distinct states — registered, KYC submitted, KYC approved (whitelisted), KYC rejected — and ensure every protected route checks against that state, not just authentication status. A user can be authenticated (valid session token) but not whitelisted, and those are two different things your middleware needs to distinguish.
Popular KYC providers for crowdfunding platforms: SumSub (strong for international, supports Ukrainian Дія gov ID), Onfido, Persona, Stripe Identity. For KYT (Know Your Transaction) on crypto-enabled platforms: Chainalysis, Elliptic, or TRM Labs — wire KYT to every inbound deposit so each transaction receives an AML risk score before the balance is credited.
Step 5: Platform Architecture and Core Features
User Registration and Authentication
Registration flow should be minimal at entry — email + password or OAuth (Google, Apple) — with progressive profile completion. The KYC step should be triggered contextually (when the user first attempts to invest), not as a registration blocker. This reduces drop-off at acquisition and defers the friction to the point where the user has demonstrated intent.
Authentication requirements for a compliant platform:
- 2FA mandatory for all financial actions (2FA via SMS, TOTP app, or hardware key)
- Email verification with time-limited tokens
- Session management with explicit logout and device tracking
- Anti-phishing measures (personalized security phrases, login notifications)

Campaign / Project Listing
The listing module is the public face of your platform. Each campaign card needs: title, category, target amount, amount raised, percentage funded, days remaining, campaign thumbnail, and a clear CTA. Full campaign pages need: rich media support (video, image gallery), markdown or WYSIWYG description, team profiles, financial breakdown, reward tiers (for reward-based), legal documents (for equity), and a comment/update section.
For equity and real estate platforms, add a financial data block: projected return, distribution period, investment minimum, tokens available (for tokenized assets), and deal documents (PPM, LLC Operating Agreement, Subscription Agreement).

Account Dashboard and Portfolio Management
The investor dashboard needs to surface: active investments with current status, total portfolio value, transaction history, reward/return status, and document access. For equity platforms, add: investment certificate download, K-1 tax document generation (for US LLCs), and distribution history.
Campaign creator dashboards require: funds raised vs. goal (real-time), backer count, traffic analytics, message inbox, update publishing, and payout request flow.

Payment Infrastructure
Payment gateway selection is determined by your geography, transaction volume, and asset types. For US-focused platforms: Stripe (credit/debit, ACH), Dwolla (ACH bank transfers, lower fees for large transactions), PayPal (broad user familiarity). For platforms accepting crypto: integrate directly at the node level (BTC, ETH, USDC) or via a processor like Coinbase Commerce or BitPay.

For international platforms beyond North America and Western Europe, add regional gateways: MangoPay (EU), LemonWay (EU regulated payments), Razorpay (India), 2C2P (Southeast Asia).
Safety, Support, and Dispute Resolution
Support infrastructure for a financial platform is not optional. Users who can't get answers about their money will reverse charges, file regulatory complaints, and leave reviews that kill conversion. Minimum viable support stack: ticketing system (Zendesk or Intercom), dedicated FAQ for financial questions, dispute escalation workflow with defined SLAs, and a documented refund/cancellation policy.

Step 6: Financial Module Architecture
This is the module that separates a working demo from a production-ready platform. It is almost always underspecced in the initial brief and overruns in development.
Escrow Logic
All-or-nothing campaigns require a proper escrow implementation: funds are authorized (or captured to a held state) at pledge time, and either transferred to the campaign creator on goal completion or released back to backers if the campaign closes below target. This is not the same as a standard e-commerce payment capture — the settlement window can be 30–90 days, which means you need payment processor support for extended authorizations or a separate held-funds account with clear accounting.
Distribution Engine
For equity and lending platforms, the distribution engine is the backend module that calculates and executes payouts to investors. Inputs: total amount to distribute, investor records with token/share counts, fee deductions. Output: individual payment instructions to each investor's wallet or bank account. The engine must handle: proration (partial distributions), currency conversion (if investors are in different currencies), tax withholding (for US LLCs, K-1 allocation), and failed payment retry logic.
Step 7: Smart Contracts and Asset Tokenization
If your platform uses blockchain for asset representation — tokenized real estate, equity tokens, or reward NFTs — the smart contract layer is a critical architectural component, not an add-on.
In our experience building a tokenized real estate crowdfunding platform, the smart contract choice has direct legal consequences, not just technical ones. We used ERC-1155 on Binance Smart Chain to represent fractional property ownership — each token series mapped to a single physical property held by a separate Series LLC. This one-to-one mapping between legal entity and token series is what makes the structure compliant: each investor's token represents a documented membership interest in a discrete LLC, not a vague "platform share".
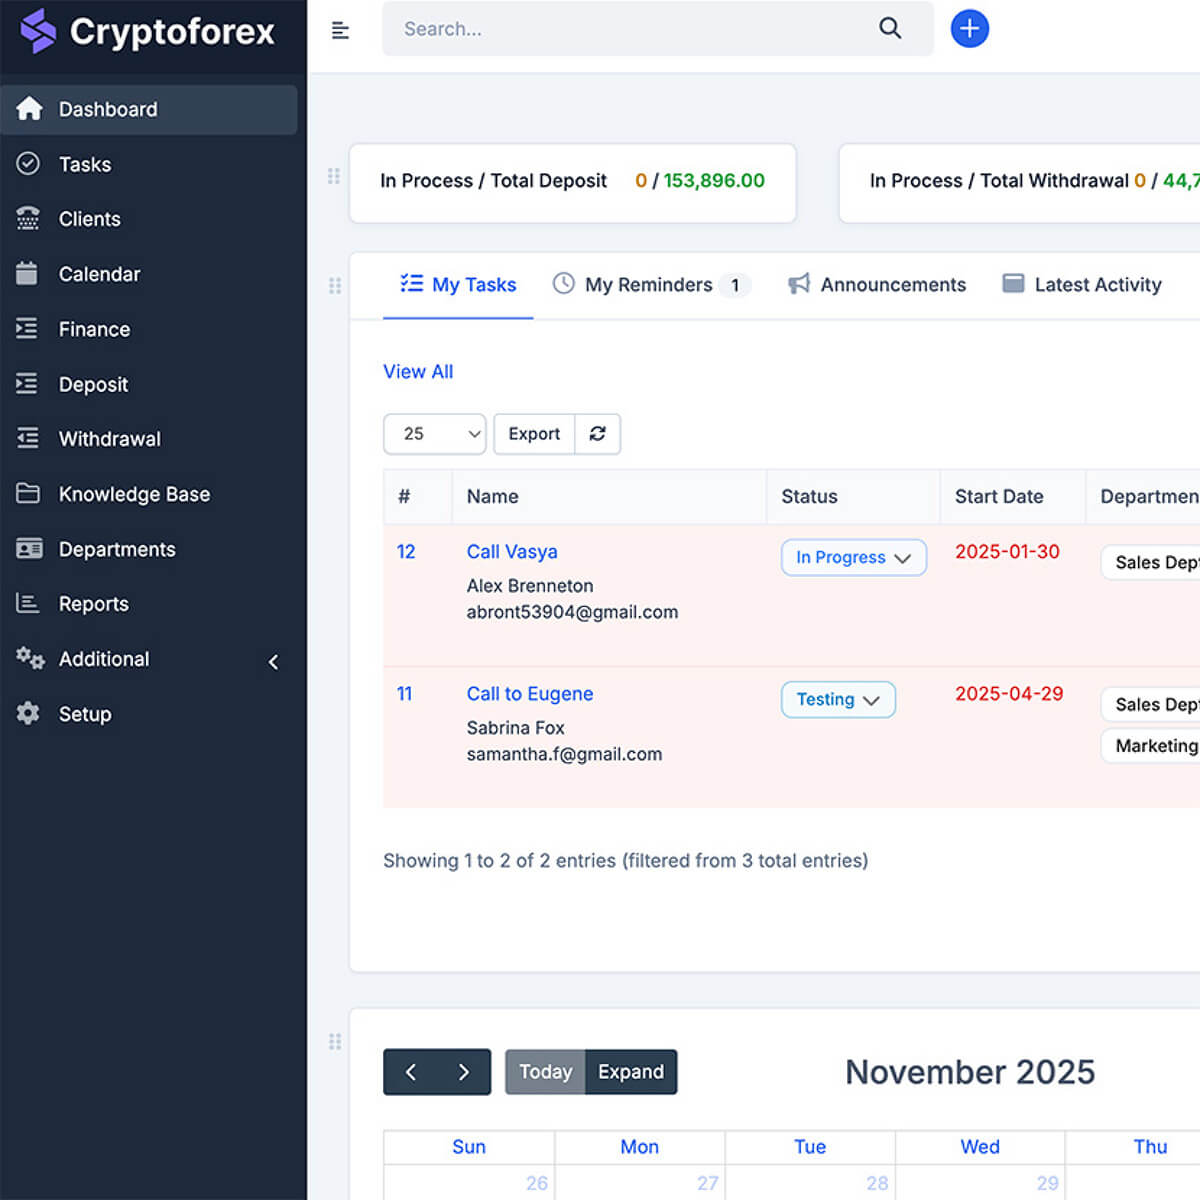
Yuri MusienkoBusiness developer, MereheadThe admin panel controls token issuance and pricing per property. When a property is listed, the admin sets total token supply, price per token, and offering period. After the primary offering closes, the secondary market activates — token holders can post buy/sell orders, and the platform auto-matches them based on price and quantity.
One architectural decision worth making early: whether to use true on-chain NFTs (each transfer recorded on-chain) or a hybrid model where ownership is tracked in your database and blockchain is used only for settlement events. Full on-chain is more transparent and auditable; hybrid is faster and cheaper to operate. For SEC-regulated platforms targeting US accredited investors, full on-chain is typically the right call — the audit trail is built into the protocol.
Smart Contract Audit
Any smart contract that handles real investor funds must be audited by an independent security firm before deployment. This is not negotiable for platforms operating under SEC or equivalent regulation. Budget $15,000–$50,000 for a professional audit depending on contract complexity. Timeline: 2–4 weeks. Plan this into your launch schedule — it cannot be parallelized with contract development.
Step 8: Tech Stack and Development Approach

Three development paths exist, each with a different cost/control tradeoff:
| Approach | Timeline | Cost range | Control | Best for |
|---|---|---|---|---|
| White-label / existing platform | 2–6 weeks | $5K–$30K setup + monthly SaaS | Low — limited customization | Donation or reward-based niche with no custom compliance requirements |
| Custom build on existing framework | 3–6 months | $40K–$120K | High | Equity, lending, or tokenized platforms requiring custom compliance flows |
| Full custom from scratch | 6–12 months | $80K–$300K+ | Maximum | Platforms at scale needing proprietary matching engines or regulatory-first architecture |
Recommended Tech Stack for a Custom Platform
- Frontend: React or Next.js — component library allows reuse across campaign pages, dashboards, and admin panel
- Backend: Node.js (Express/NestJS) or Python (Django/FastAPI) — both have mature payment and blockchain library ecosystems
- Database: PostgreSQL for transactional data (investments, payments, user accounts); Redis for session management and real-time balance caching
- Blockchain: Ethereum / BSC for ERC-20/ERC-1155 tokens; use Hardhat or Foundry for contract development and testing
- Infrastructure: AWS or GCP — ECS/EKS for containerized services, RDS for managed Postgres, S3 for campaign media
- KYC: SumSub or Onfido via API — webhook-driven state updates to your user verification service
- Payments: Stripe (fiat) + direct node integration or Coinbase Commerce (crypto)
Admin Panel Scope
The admin panel is as complex as the user-facing product — and consistently underspecced. Production-grade admin requirements for a compliant investment platform:
- User management: KYC status, whitelist approval/rejection, account freeze
- Campaign management: listing approval, token supply configuration, offering period control
- Financial controls: fee configuration, distribution triggers, manual payout approval
- Transaction monitoring: AML alerts, flagged deposit review, wallet management
- Role-based access: compliance officer, financial admin, support agent, read-only auditor
- Reporting: investor count per campaign, funds raised, distribution history, K-1 data export
Step 9: Development Costs and Timelines
A production-ready crowdfunding platform is not a 4-week sprint. In our real estate tokenization project — web platform, admin panel, iOS and Android apps, smart contract, KYC integration, dual-currency wallets, secondary market order book — the complete timeline was 3 months with a full-stack team. That covers MVP scope, not a feature-complete product.
The modules that consistently drive timeline and cost overruns are: the financial accounting layer (multi-currency, multi-balance), KYC/compliance integration, smart contract development and audit, and the admin panel. Teams that treat the admin panel as an afterthought are the ones that go over budget and over time.
| Platform scope | Timeline | Cost estimate | What's included |
|---|---|---|---|
| Basic MVP | 2–3 months | $20,000–$40,000 | Campaign listing, investment flow, user accounts, basic admin panel, one payment gateway |
| Full-featured platform | 3–5 months | $40,000–$80,000 | Multiple payment methods (crypto + fiat), KYC integration, advanced filtering, analytics dashboard, full admin |
| Kickstarter-class platform | 5–7 months | $80,000–$140,000 | All above + secondary market, mobile apps (iOS/Android), smart contracts, compliance module, audit |
| Scalable / cluster architecture | 8–14 months | $140,000+ | Microservices, Kubernetes orchestration, multi-region deployment, millions of users capacity |
FAQ
It depends on your model. Donation and reward-based platforms generally don't require SEC registration. Equity crowdfunding platforms must register as a FINRA Funding Portal (under Reg CF) or as a broker-dealer. Platforms raising under Reg D (private placements, accredited investors only) file Form D but don't require full SEC registration. Consult a securities attorney before launch — platform operators are liable for compliance failures, not just campaign creators.
A true MVP needs: user registration with email verification, campaign creation and listing, a payment gateway (Stripe is sufficient to start), an escrow mechanism (all-or-nothing or flexible), an investor/backer dashboard with transaction history, and an admin panel for campaign and user management. KYC is mandatory from day one if you're running equity or lending campaigns. Everything else — secondary markets, mobile apps, advanced analytics — is a post-MVP iteration.
A Kickstarter-equivalent platform with full campaign management, multiple payment methods, mobile apps, and a complete admin panel typically costs $80,000–$140,000 and takes 5–7 months with a full-stack team. A basic MVP without mobile apps and with a single payment gateway can be built for $20,000–$40,000 in 2–3 months. The largest cost drivers are the financial module, KYC integration, and admin panel — these three components alone often represent 50–60% of total development time.
For real estate and equity tokenization, Ethereum mainnet offers the strongest audit trail and institutional familiarity, but gas costs are meaningful at scale. Binance Smart Chain (BNB Chain) is a common choice for cost-sensitive projects — lower transaction fees, EVM-compatible, broad wallet support. For US SEC-regulated platforms, ERC-1155 (multi-token standard) allows mapping each token series to a separate legal entity, which is the compliant architecture for fractional ownership. Whichever chain you choose, an independent smart contract audit ($15K–$50K) is mandatory before handling investor funds.
Integrate a KYC provider (SumSub, Onfido, or Persona) via API, driven by webhooks that update user verification status in your backend. Design your user state machine with at least four states: registered, KYC submitted, KYC approved (whitelisted), and KYC rejected. Every investment flow must check whitelist status — not just authentication. For crypto-enabled platforms, add KYT (Know Your Transaction) to every inbound deposit: each transaction receives an AML risk score before the balance is credited to the user's account. Deposits above the risk threshold should be queued for compliance officer review, not auto-credited.
Yes, but you need either a development agency with fintech experience or a white-label solution as your starting point. The risk of hiring freelancers for a financial platform is real: compliance architecture, payment security, and smart contract integrity require domain experience, not just coding skill. If you go with an agency, verify they've shipped at least one production investment or payment platform — the architecture decisions that matter most don't show up in a portfolio screenshot.
Reg CF (JOBS Act Title III) allows raising up to $5M per year from both accredited and non-accredited investors; platform must be a registered FINRA Funding Portal. Reg A+ (Tier 2) allows up to $75M per year with lighter restrictions on non-accredited investors, but requires SEC qualification and ongoing reporting — it functions like a mini-IPO. Reg D (506b/506c) has no raise cap but restricts participation to accredited investors only; Rule 506c allows general solicitation but requires verified accreditation for every investor. Choose based on target raise amount and investor base — most early-stage equity platforms start with Reg CF or Reg D 506b.
A basic reward or donation platform takes 2–3 months. A full equity or real estate crowdfunding platform with KYC, compliance controls, dual-currency wallets, smart contracts, and mobile apps takes 5–7 months for a first production release. This assumes a team of 4–6 engineers working full-time. The single biggest timeline risk is smart contract audit — it takes 2–4 weeks and cannot be parallelized with the final development phase. Start the audit process early.